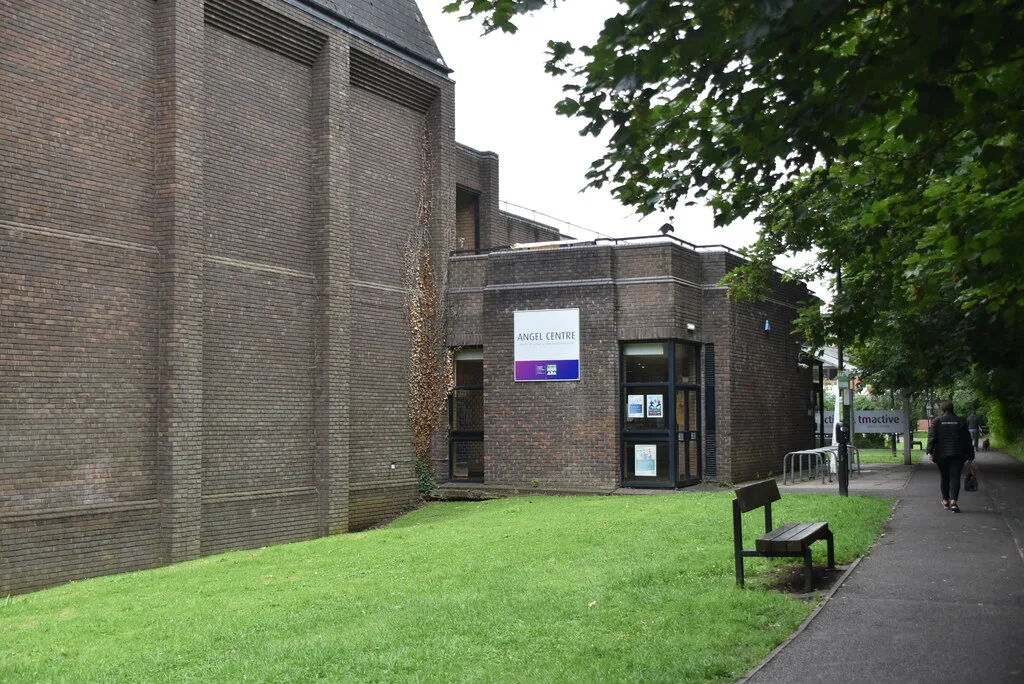

The auditor says councillors lack a funding plan for the £19.4m Angel Centre rebuild. Audit Committee accepted all three fixes on 28 September; Cabinet takes it on 6 October.
The new Angel Centre in Tonbridge is now estimated to cost £19.4m. The council’s external auditor says councillors have not yet been shown how it will be paid for.
Updated 2 October: the Audit Committee met on 28 September and sent the auditor’s report on to Cabinet on 6 October. Management Team has accepted all three improvement recommendations, including the one on reporting how big capital projects are funded and what they will cost to borrow for. The Angel Centre business case is not on the 6 October Cabinet agenda, and it is not named in the council’s notice of key decisions for November and December. Grant Thornton’s report still says it “expects” to sign an unqualified opinion on the accounts; we have not yet seen the signed version. (Cabinet supplement, Audit Committee recommendations; Cabinet agenda, 6 October 2026; Notice of forthcoming key decisions, November to December 2026)
That finding is in the papers for Tonbridge and Malling Borough Council’s Audit Committee, which meets on Monday 28 September. It is the only council meeting in the borough in the next seven days. (Audit Committee, 28 September 2026)
Audit Committee: Monday 28 September, 7.30pm
The committee meets in the Council Chamber at Gibson Drive, Kings Hill. The public can attend. Here is what is on the agenda, and what matters for residents.
The Angel Centre: £19.4m, and borrowing “may be required”
Grant Thornton, the council’s auditor, calls the Angel Centre rebuild “the Council’s largest planned capital investment”. Its annual report gives the figures:
- total estimated cost: £19.4m
- of which £15.0m is profiled for spending in 2026/27
- financing options “remain under development”
- borrowing “may be required during the project life-cycle”
The auditor adds that the running cost of any borrowing is “not yet fully reflected” in the council’s Medium-Term Financial Strategy. Without a funding plan, it says, councillors “have less visibility over the potential impact of the Angel Centre project on borrowing, reserves and the MTFS”. (Grant Thornton Auditor’s Annual Report 2025/26)
The council has accepted the point. Its response promises “a comprehensive business case” in October 2026. That will set out the full project cost, how it will be funded, whether it is affordable, and the effect on the fee income the council receives from its leisure services. (Head of Finance report)
When full council granted planning permission in July, the council’s own announcement put the investment at £20 million. The final decision to build is due at full council on 20 October. Our earlier report covers what the planning permission allows.
The rest of the auditor’s verdict
The auditor found no significant weaknesses in how the council runs its finances or its governance. It made three recommendations for improvement:
- better reporting to councillors on how big capital projects are funded (the Angel Centre point)
- best-case, central and worst-case scenarios for the council’s main budget assumptions, due by February 2027
- a fuller Annual Governance Statement, due by March 2027
All three recommendations from the previous year have been closed. Grant Thornton expects to sign off the 2025/26 accounts with an unqualified opinion after Monday’s meeting.
The Local Plan is now the council’s only red risk
The council keeps a strategic risk register. In July, two risks were rated red:
- failure to adopt a Local Plan
- local government reorganisation in Kent
Reorganisation has now dropped out of red. The council says the government’s pause of the Kent process “has reduced the likelihood”, although the impact stays high. (Risk management report)
That leaves the Local Plan as the only red risk. It scores 20 out of 25 before mitigation and 15 after. The register says some infrastructure providers’ position is that what the plan needs “is not achievable in line with Local Plan timescales”. It lists “potential for central Government intervention” as one effect, which has already happened. (Strategic Risk Register, red risks)
Our reports on the plan so far: the government’s intervention and the Regulation 19 consultation and the water shortfall.
Two smaller accounting points
- Housing Benefit timing. The audit found £0.206m of Housing Benefit spending from 2024/25 booked in 2025/26. It was not large enough to change the accounts, but the auditor wants the year-end process tightened.
- Pensions. The auditor asked for an extra note on the council’s pension position. The accounts carry an “asset ceiling” adjustment of £17.462m, leaving a net pension liability of £2.430m. The council says the note is disclosure only and changes no figures.
(Audit findings report; pensions supplementary report)
The committee will also note a mid-year treasury management update on the council’s investments.
Coming next
Agendas for these meetings are not published yet. We will cover them when they are.
| Meeting | Date | Time |
|---|---|---|
| Cabinet | Tuesday 6 October | 7.30pm |
| General Purposes Committee | Wednesday 7 October | 7.30pm |
| Housing and Planning Scrutiny Select Committee | Tuesday 13 October | 7.30pm |
| Planning Committee | Wednesday 14 October | 7.30pm |
| Full Council | Tuesday 20 October | 7.30pm |
(Council meetings calendar, October 2026)
What it means for you
- If you use the Angel Centre, the business case due in October is the first time the council will say in public how the £19.4m will be found. Watch for it on the Cabinet and full council agendas.
- If you want to go on Monday, the meeting is public, at Gibson Drive, Kings Hill, at 7.30pm. Questions on the accounts are meant to reach the report authors before the meeting. Contact committee.services@tmbc.gov.uk.
- If you pay council tax, the auditor’s clean verdict means no significant weaknesses were found in how your money is managed. The open question is borrowing for the leisure centre.
More local council information: council tax bands and planning applications this week.
Sources: Audit Committee agenda, 28 September 2026; Grant Thornton Auditor’s Annual Report 2025/26; Risk management report and red risk register; Tonbridge and Malling council meetings calendar.
Have your say